You send statements and tax returns into a process you cannot see, and get back an answer with no real explanation.
Turned down before? Applying soon? Read this first.
Walk in knowing exactly how lenders decide.
You send in the statements. You wait. Then a "no" with no real reason, or terms that do not fit. Most business loans are won or lost before the meeting, and nobody hands you the lender's checklist. Before You Borrow does: what they check, what quietly gets applications declined, and how to build a file that makes a yes easy to say.
$7.99one-time · instant PDF
Get Instant Access
- Instant download
- Emailed to you
- Secure checkout by Square
- 28 pages, no fluff
$7.99Instant
PDF
Why good businesses still get a "no."
You know your business better than anyone. But a loan officer reads it through a checklist you never see, and nobody explains that checklist before you apply.
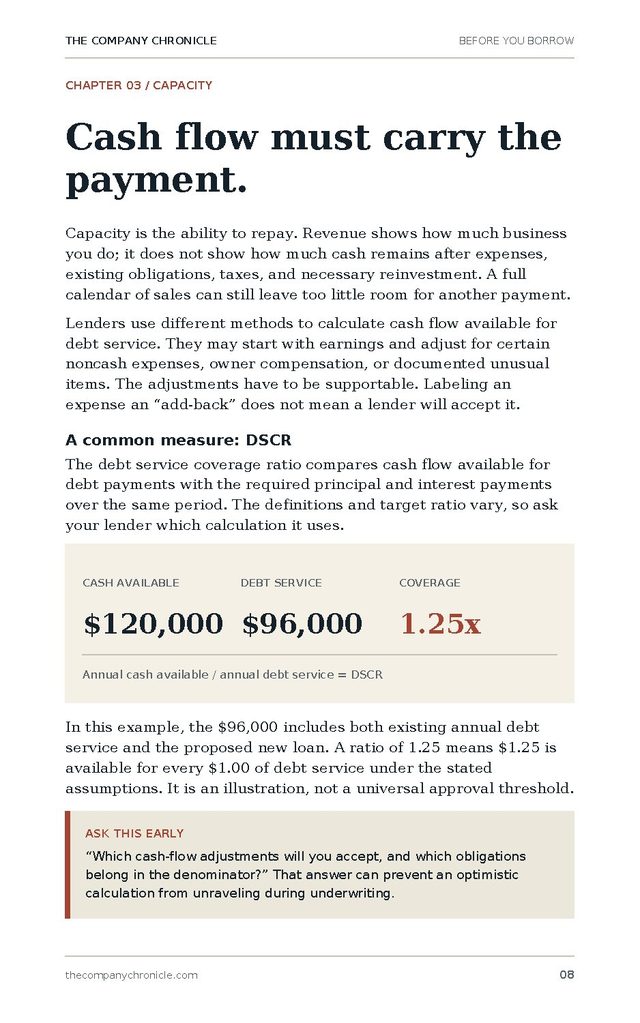
A busy sales calendar can still leave too little cash to carry another payment. Lenders measure the cash, not the hustle.
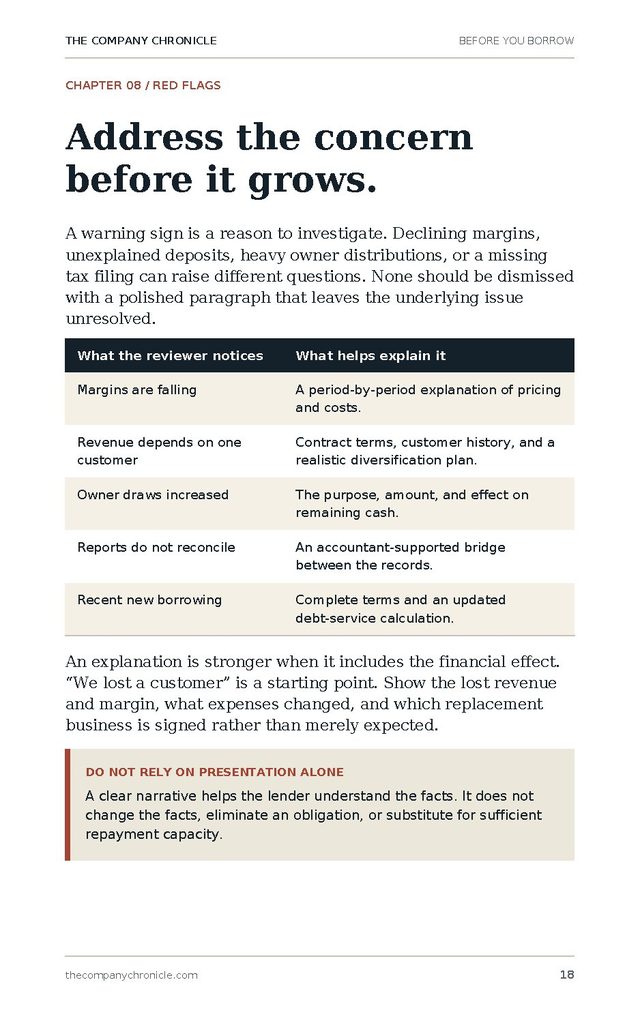
Records that do not match, a late payment with no explanation, or a vague "we want to grow" can turn a maybe into a decline.
The framework lenders use
Learn the five Cs of credit, in plain English.
Every chapter turns one question the lender is asking into something you can prepare, prove and explain.
CharacterCan your record be trusted?
CapacityCan cash flow carry the debt?
CapitalWhat cushion backs the plan?
CollateralWhat secures the loan?
ConditionsDoes the purpose fit the moment?
What is inside the book
- 01Start with a clear business purpose
- 02Character: build trust with evidence
- 03Capacity: cash flow must carry the payment
- 04Capital: keep a cushion behind the plan
- 05Collateral: understand the lender's backstop
- 06Conditions: put the business in context
- 07Build your financial package
- 08Address the red flags
- 09Manage the banking relationship
- 10Choose the financing structure
- 11Your 30-day preparation plan
- +Plain-English lending glossary
After reading it, you will be able to:
Practical steps you can use this week, whether you are applying to a bank, a credit union, an SBA lender or an online funder.
- Write a one-page request brief that tells the lender the amount, the use, the timing and how you will repay.
- Check your debt service coverage (DSCR) the way lenders do, before they do.
- Explain a credit issue the right way: what happened, what changed, and the proof.
- Assemble a complete financial package with the document checklist, so nothing holds up review.
- Spot the red flags reviewers notice first, like falling margins or reports that do not reconcile.
- Pick the right structure for what you are funding instead of the first offer you see.
- Follow a 30-day plan: define, reconcile, document, then talk to lenders.
- Read loan terms with confidence using the plain-English glossary: covenants, guarantees, balloons and more.
Take a look inside.
Clean, readable pages with worked examples, checklists and tables you can use with your own numbers.
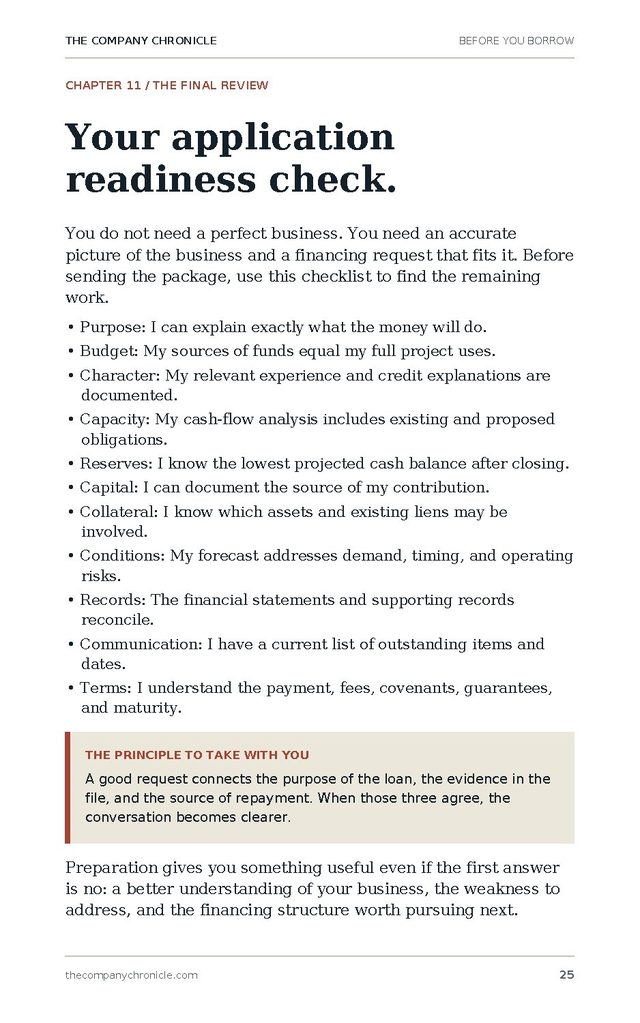
"You do not need a perfect business. You need an accurate picture of the business and a financing request that fits it."
From Chapter 11, Before You BorrowIs this book for you?
Yes, if you are:
- About to apply for a business loan, line of credit or SBA loan
- Turned down before and want to know what to fix
- A first-time borrower who wants to sound prepared
- Buying equipment, a location or another business
- Tired of generic advice that skips how lenders really think
Probably not, if you want:
- A promise of approval (nobody honest can make one)
- A personal loan or mortgage guide
- Legal or tax advice for your specific situation
- A 300-page textbook. This is 28 focused pages.
Instant digital download
Get Before You Borrow today.
Less than the cost of lunch, and it could change how your next loan conversation goes.
- 28-page PDF guide, read on any device
- The five Cs of credit, explained simply
- Document checklist and red-flag table
- 30-day preparation plan and readiness check
- Plain-English lending glossary
$7.99one-time
Yes, Send Me the Book
Secure checkout by Square. Download on screen and by email right after payment.
Questions
How do I get the book after I pay?
Right after your payment is confirmed, a download button appears on the screen, and the PDF is emailed to you from The Company Chronicle. Keep that email for your records.
What do lenders look at when deciding on a business loan?
Most lenders work through the five Cs of credit: character, capacity, capital, collateral and conditions. The book explains each one in plain English and shows how to turn it into evidence in your application.
Why do business loans get declined?
Common reasons include cash flow that cannot carry the payment, records that do not reconcile, unexplained credit issues, a vague purpose for the money, or asking for the wrong product. The book shows how to spot and address these before you apply.
Will this guarantee my loan gets approved?
No, and be careful with anyone who says otherwise. Lenders decide based on your business and their rules. This guide helps you prepare a clearer, better-supported request, so you understand the decision and what to work on next.
Does it work for SBA loans, banks and online lenders?
Yes. The five Cs and the preparation steps apply broadly. Requirements differ by lender and program, so the book shows you which questions to ask each one.
What format is it, and can I read it on my phone?
It is a PDF, 28 pages, and it reads well on a phone, tablet or computer. You can also print it.
I did not get my email. What should I do?
Check your spam or promotions folder first. If it is not there, reply to any Company Chronicle email or contact us with the email you used at checkout and we will resend it.