Freddie Mac: 7.24% mortgages still cost $284 more a month than a year ago
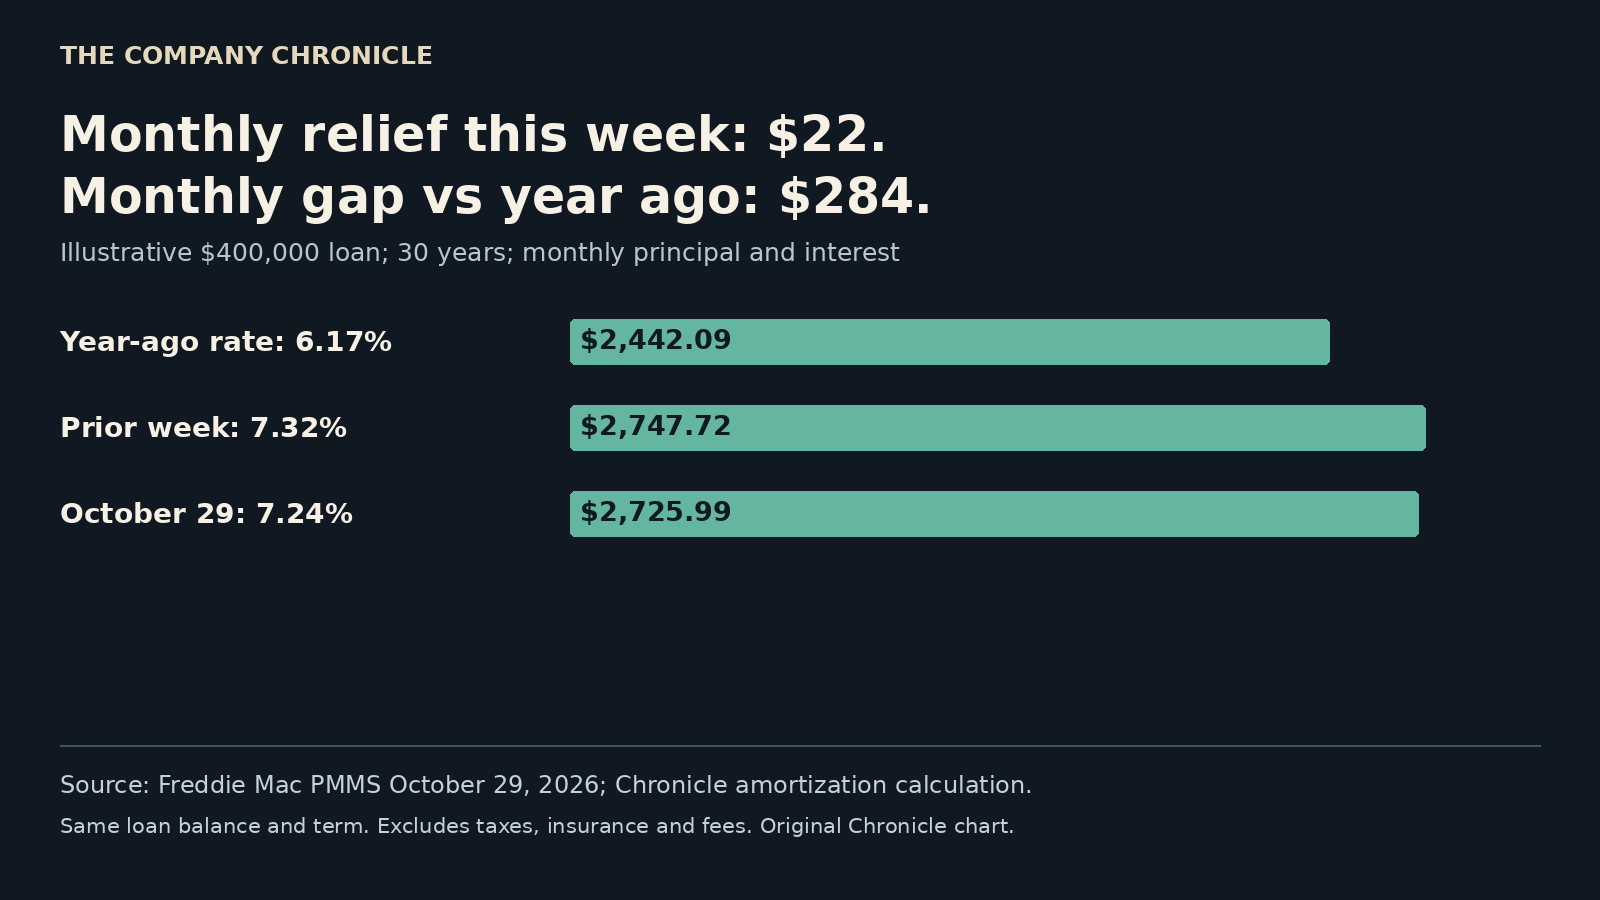
The weekly 30-year average fell another eight basis points. On an illustrative $400,000 loan, that trims about $22 monthly, much less than the increase from last year's rate.
The average 30-year fixed mortgage rate fell to 7.24% in Freddie Mac's October 29 survey, down from 7.32% a week earlier. The 15-year average declined to 6.60% from 6.68%. It is another small improvement for someone arranging a home loan, rather than a return to last year's borrowing cost.
Freddie Mac's Primary Mortgage Market Survey puts the year-ago 30-year rate at 6.17%. Keeping the loan balance and repayment term unchanged, that difference matters considerably more than this week's eight-basis-point decline.
Same loan, three different monthly bills
For a hypothetical $400,000 mortgage repaid in 360 equal monthly installments, principal and interest are $2,725.99 at 7.24%. At last week's 7.32%, the payment is $2,747.72. The weekly improvement is therefore $21.73 a month, or $260.76 over twelve payments.
| Rate comparison | Annual rate | Monthly principal and interest |
|---|---|---|
| October 29 survey | 7.24% | $2,725.99 |
| Previous week | 7.32% | $2,747.72 |
| Year-ago comparison | 6.17% | $2,442.09 |
The present payment is $283.90 higher than the payment at the year-ago rate, approximately $3,407 across twelve months. Those calculations hold the amount borrowed fixed. They say nothing about changes in home prices, down payments, credit scores or loan fees.
They also exclude property taxes, homeowners insurance, mortgage insurance and closing costs. A lender's actual offer can differ from the national average. The table is a like-for-like rate comparison, not a quote or an eligibility assessment.
What the weekly survey measures
Freddie Mac draws the survey from mortgage applications submitted through its Loan Product Advisor system. Results are published on Thursdays at noon Eastern, covering the preceding Thursday through Wednesday. The agency describes the national average as drawn from conventional single-family purchase applications meeting its criteria.
That makes 7.24% a weekly benchmark, not a promise about a Thursday evening rate lock. Someone comparing offers needs to compare the same loan amount, term and fee structure. A cheaper advertised rate accompanied by higher upfront charges can be a different bargain from the one implied by the headline.
The longer comparison remains expensive
The yearly rise in the 30-year average is 1.07 percentage points, or 107 basis points. For the 15-year product, the year-ago rate was 5.41%, compared with 6.60% in the latest release. Comparing the two maturities only by their interest rates misses their different repayment schedules; the shorter term has fewer payments in which to repay the principal.
For a buyer still shopping, the immediate gain is a modest reduction in the modeled payment. For someone with an existing rate lock, the survey does not change the signed terms. Any opportunity to revise that lock depends on the lender's actual agreement and charges.
Readers tracking the broader rates backdrop can consult our 10-year Treasury chart. This article does not assign a cause to the weekly mortgage move without a matching bond-market analysis. The verified finding is narrower: the benchmark eased, but the year-over-year financing burden remains substantially larger than this week's relief.
Source: Freddie Mac PMMS, October 29, 2026. Payment calculations use the standard fixed-payment amortization formula with a $400,000 principal, annual rate divided by twelve and 360 payments. Figures rounded to cents; comparisons are calculated before rounding. This is housing information, not investment advice.
Want your business to be the answer?
Get a full package of articles about your business, built so customers, Google and AI assistants can find you.
 New ebook from The Company ChronicleHow to Research Like a Wall Street AnalystFind original sources, analyze trends, and build your own insights. 36 pages with worksheets.Get the ebook · $29Instant PDF download